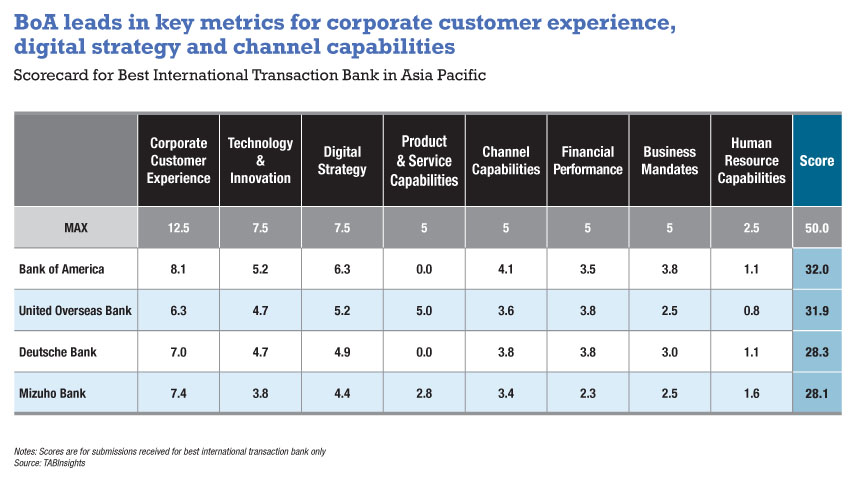
BoA, UOB and Deutsche Bank are the winning transaction banks in Asia Pacific in The Asian Banker Best Transaction Bank Rankings 2023, with leading positions in customer experience, technology and innovation, and digital capabilities
Central banks worldwide increasingly recognise the benefits of wholesale central bank digital currencies (wCBDCs) in making remittances and other cross-border transactions cheaper, faster and safer. Pilot projects set in motion seek to identify opportunities and risks as well as explore the possibility of having shared infrastructure to automate cross-border payments, foreign exchange and settlements.
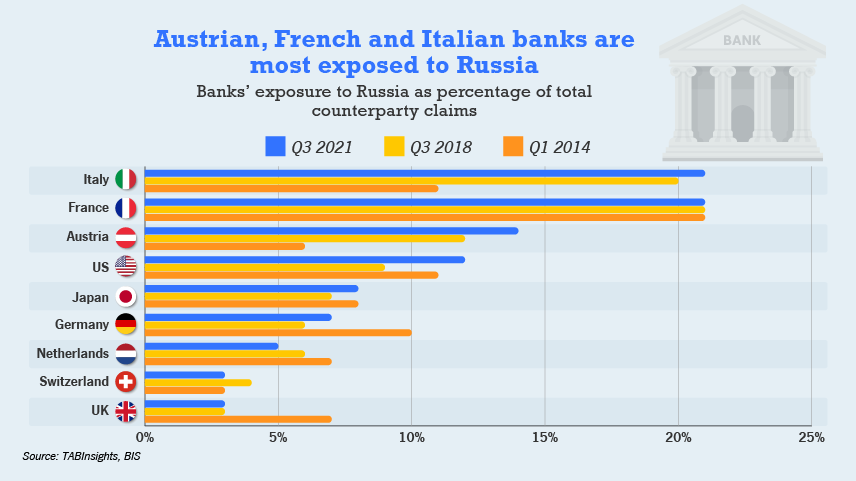
The prospect of a ban on Russia from SWIFT becomes ever likely as its attack on Ukraine escalates. However, the impact of such an outcome will not only be felt by the Russian economy and financial system but also banks, mostly European, that have significant exposures to it.
As global banks move towards ISO 20022 readiness by the end of 2022, it is important to understand the impact that the adoption of the new standard will have on the banking and payment industries and what challenges and opportunities they will face as they modernise international settlement.
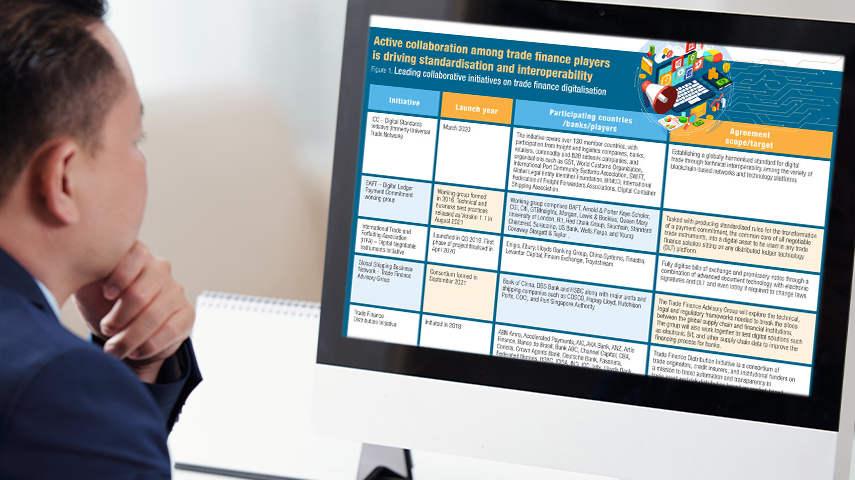
As the trade finance industry collectively progresses to address challenges around digital fragmentation and isolation, adoption of standard solutions and well-established legal frameworks along with technology as an enabler will play critical roles in truly digitalising trade.
As demand for sustainable products rises, stakeholders including consumers, investors, and regulators are pushing manufacturers, suppliers and lenders to incorporate ESG metrics in evaluating the performance of their supply chains.
Industry practitioners discuss how process of bringing offshore global supply chains back to the country of origin accelerates demand for existing and new financing programmes that provide liquidity for sub-tier level of suppliers
Customers make decisions on primary banking relationship based on assumed needs for multiple network point convenience, even though they may patronise one point most often. In the debate over the role and future of bank branches, ultimately the only opinion that counts is the consumer’s.
Africa’s payments services architecture is rapidly evolving in response to changing technology and customer expectation. While non-banks such as mobile network operators (MNOs) are the key drivers of disruptive payments technologies in Africa, traditional banks are also creatively developing and integrating disruptive technologies to address the continent’s payment challenges and most importantly meet customer expectations.
While fintechs may take some market share away in specific niches, the partnerships, analytics, and value-add that leading banks are developing can keep head of the game. Banks that fail to keep up could lose a significant share of their SME business
Chinese credit card industry exploded over the past two years, with growth rates being recorded in the number of credit cards issued and outstanding credit card debt, as well as the income from credit card business.
As real-time processing becomes the norm in domestic payments, how long would it take for cross-border payments to catch up?